


PAVAN AGNI elaborates on why the current gold cycle is about much more than war, inflation and interest rates – and why India’s attempt to curb gold imports raises a larger question about household savings
Gold is usually explained through a familiar list of variables: interest rates, inflation, the dollar, geopolitical tensions and central-bank purchases. Yet none of these, individually, explains the current cycle. Gold has evolved into something more complex – simultaneously a commodity, financial asset, reserve asset and, particularly in India, a form of household insurance.
The most consequential change is taking place in central-bank reserve rooms. Since the Ukraine war, several central banks have accelerated gold accumulation as a hedge against currency, geopolitical and sanctions-related risks. Global gold demand in the first half of 2026 reached 2,522 tonnes, worth a record $380 billion, while central banks added 289 tonnes in the second quarter alone. Jewellery demand, meanwhile, has weakened as high prices reduce affordability.
The distinction is important. Traders buy gold for price movement; investors buy it for diversification; central banks buy it because, unlike a bond or bank deposit, gold is nobody else’s liability. And households often buy it for an even older reason: insurance against an uncertain future.
Gold and crude: two sides of India’s external balance sheet
For India, gold becomes particularly interesting when viewed alongside crude oil. India has a structural dependence on imported energy. Crude feeds transport, aviation, petrochemicals, manufacturing and logistics. When oil prices rise, India’s import bill increases, inflationary pressure builds and the rupee can come under pressure.
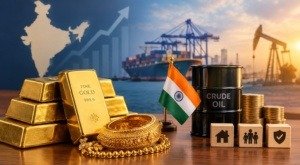 Gold behaves differently. It is not an unavoidable industrial input. A family can postpone buying jewellery or an investor can delay buying an ETF. But postponing consumption does not necessarily eliminate the desire to own gold. In periods of geopolitical or economic stress, the same environment that makes crude more expensive can make gold more attractive.
This creates a policy paradox. The government sees gold as an import that consumes foreign exchange. The household may see it as protection against precisely the economic shocks that threaten its purchasing power.
Why India raised the duty – and the uncomfortable comparison
The rationale behind India’s increase in gold duty from 6% to 15% in May is straightforward. India imports almost all the gold it consumes. If higher taxation reduces demand, fewer dollars leave the country. At a time of elevated oil prices and pressure on the trade deficit, reducing discretionary imports has an obvious attraction.
But demand does not necessarily disappear when taxation rises; it can change channels. A large gap between legally imported and unofficially sourced gold can create an incentive for smuggling, weaken formal players and move economic activity outside the regulated system.
More importantly, gold should not be viewed in isolation from India’s much larger import appetite for electronics. In FY2023-24, India imported about $45.5 billion of gold, but also more than $50 billion of electronic and telecom appliances. The economic character of these imports is very different. Gold converts domestic savings into a globally recognised store of value. An imported smartphone, by contrast, is a rapidly depreciating consumer product. That distinction suggests a more nuanced policy approach. Rather than imposing a steep increase on gold, India could focus more aggressively on reducing avoidable imports of finished electronics and mobile phones wherever domestic alternatives are viable, while keeping duties on productive intermediate components calibrated to encourage manufacturing rather than simply raise costs.
The question is therefore not whether India should import less. It is whether India is taxing the imports that are easiest to substitute – or simply the ones that are easiest to tax.
Let households decide how to save
There is an even deeper issue. Gold is not merely a luxury purchase for millions of Indian families. It has traditionally been a decentralised form of financial insurance – portable, liquid, globally recognised and independent of any particular bank, company or currency.
Government has every right to manage India’s external balance and encourage productive investment. But there is a difference between redirecting savings through attractive alternatives and penalising a savings choice through taxation.
A household that chooses gold may be making a different assessment of risk from a policymaker. It may be protecting itself against inflation, currency weakness, financial disruption, war or simply an uncertain future. That decision should not automatically be treated as economically irrational.
A household does not invest with untaxed income. By the time money becomes savings, it has already passed through income taxes, GST and other indirect taxes.
What remains is the household’s legitimately earned and taxed wealth. How that money is allocated – into gold, equities, deposits, property or other assets – should ultimately be a matter of individual judgement and risk preference. Policy should create better choices, not dictate the choice.